
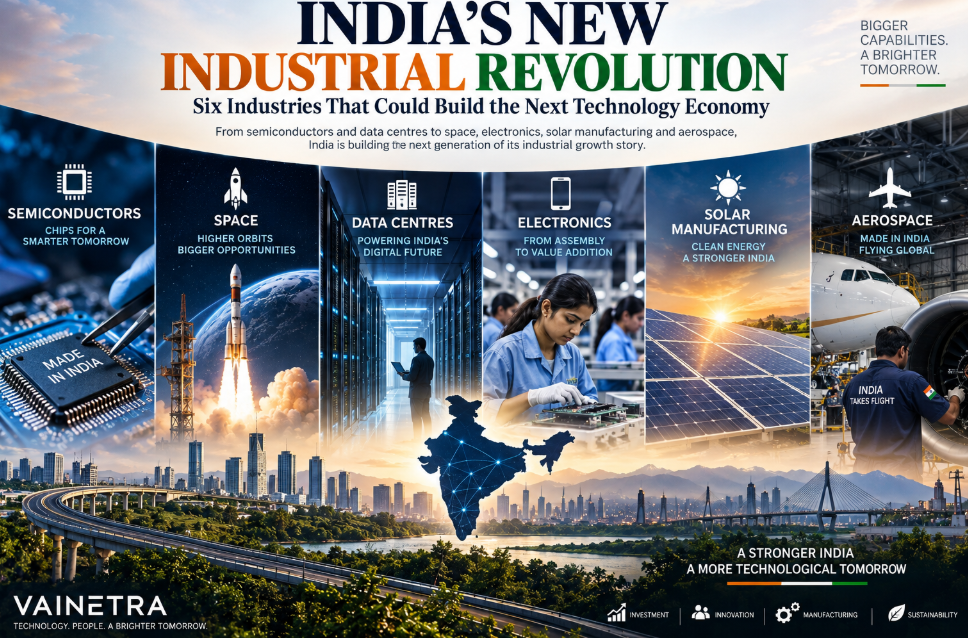
India’s next industrial revolution may not be built around a single factory, sector or technology. Instead, it is taking shape across six emerging industries that sit at the intersection of manufacturing, technology, infrastructure and national strategic priorities.
A September 8 report by Jefferies argues that India’s combination of scale, domestic demand, manufacturing capabilities and policy support is creating the foundation for new growth engines in semiconductors, space, aerospace, electronics, solar and data centres.
The shift is significant because India is not starting from a low industrial base. Jefferies points out that India is already the world’s second largest manufacturer across several established sectors, including steel, cement, automobiles and refining, while it has also emerged as a major manufacturer of mobile phones and solar modules. The next step is to use that base to move into more technology intensive industries.
That transition is already visible in investment, policy and capacity creation.
Space: From government programme to private industry
India’s space economy is moving from a predominantly government led model towards a broader commercial ecosystem. Jefferies notes that the government opened the space value chain to private participation in 2020 and expects the country’s space economy to expand around five fold between 2023 and 2030 to $40 billion to $45 billion, with a longer term target of $100 billion by 2040.
The change is already visible in the startup ecosystem. India had just one space startup in 2014. By 2026, the number had risen to more than 400, covering launch vehicles, satellites, Earth observation, propulsion and downstream applications. Cumulative private investment had reached around $600 million by FY26, according to Jefferies.
Companies such as Skyroot Aerospace, Pixxel, Agnikul Cosmos and Digantara are moving beyond early stage experimentation.
Skyroot became the first private Indian company to place payloads into orbit with its Vikram 1 launch in July 2026. Pixxel operates a constellation of high resolution hyperspectral Earth observation satellites and has secured a NASA contract. Agnikul has developed a rocket powered by a single piece 3D printed semi cryogenic engine, while Digantara has launched a commercial space surveillance satellite.
Jefferies describes the development as “Private sector launching into a higher orbit”.
The opportunity is therefore expanding beyond launches. Satellites, Earth observation, space situational awareness, propulsion, ground infrastructure and downstream data applications are creating multiple layers of the emerging space economy.
Semiconductors: Building the ecosystem, not just fabs
Few industries illustrate India’s industrial ambitions better than semiconductors. Jefferies says India’s semiconductor aspirations are moving from “policy intent to execution”, with around $20 billion of investments covering a chip fab and multiple OSAT and ATMP projects.
The first phase of India’s semiconductor incentive programme, launched in 2021 with an outlay of Rs 76,000 crore, has triggered around $20 billion of investments. Tata Electronics is constructing an approximately $11 billion semiconductor fab in Gujarat, while Micron, Kaynes Technology and CG Power have commenced commercial production at semiconductor packaging facilities.
But India’s semiconductor ambition goes beyond manufacturing. The second phase of the incentive programme has an outlay of around Rs 1.28 lakh crore, or $13 billion, according to Jefferies. It expands support to chip design, semiconductor equipment, materials, specialty chemicals, gases, advanced packaging, research and development and talent development. The government expects the programme to attract about Rs 4 lakh crore of investments, generate Rs 2 lakh crore of semiconductor and electronics production and drive Rs 1 lakh crore of exports.
One of India’s biggest advantages is design talent.
Jefferies estimates that India accounts for around 20% of the world’s semiconductor design workforce and has become a key R&D base for global semiconductor companies. A new generation of Indian startups is working on AI accelerators, power management, RF and automotive chips.
The brokerage, however, also flags challenges including an undeveloped supply chain, limited semiconductor manufacturing talent, global competition and rapidly changing technology.
Its conclusion is that India’s opportunity may initially lie not in matching the US or Taiwan at the technology frontier, but in using proven technologies to build solutions around India’s growing domestic demand.
Data centres: The infrastructure behind India’s digital economy
The AI and cloud economy needs something physical: computing infrastructure. India’s colocation data centre capacity has already increased five fold over the past five years to around 2GW, according to Jefferies. The brokerage expects another five fold increase to approximately 10GW over the next five years.
The numbers point to a much bigger investment cycle. Jefferies estimates that the expansion could create a $9 billion revenue opportunity for data centre operators and around $45 billion of facility investment across power, cooling, construction and network infrastructure. The broader requirement is even larger.
For CY27 to CY31, Jefferies estimates around $45 billion of data centre capex and another $90 billion of server capex, taking the total requirement for data centres and IT hardware to around $135 billion.
This makes the data centre opportunity much broader than a story about operators. Power equipment companies, transmission infrastructure providers, cooling companies, construction firms, real estate developers, network infrastructure companies and electrical equipment manufacturers could all participate in the expansion.
Jefferies says India’s power and capex requirements for data centres are, on average, 25% to 40% lower, while data localisation and a 20 year tax holiday for cloud providers are supporting the country’s emergence as a regional data centre hub.
Electronics: India’s next battle is for value addition
India has already demonstrated that it can manufacture smartphones at scale. The harder challenge is now to manufacture the components that go inside them. Jefferies says electronics production more than doubled over the past five years, while electronics exports increased around five fold. In FY26, electronic goods became India’s third largest export category by value, while smartphones were the country’s largest export product.
Yet there remains a major gap between assembly and value addition. Around 99% of phones sold in India are assembled domestically, but the country remains dependent on imports for several components. Jefferies says domestic value addition has so far remained below 20%. The next phase is therefore about backward integration.
The Electronics Components Manufacturing Scheme, or ECMS, is targeting around 50% backward integration in mobile phone manufacturing, compared with the much lower level today. Printed circuit boards, camera modules, display modules, enclosures, batteries and other components are among the areas receiving attention.
Jefferies estimates the PCB opportunity alone at around $5 billion, with 85% to 90% of requirements currently imported. The significance goes beyond smartphones. A deeper component ecosystem could eventually support computers, servers, networking equipment, industrial electronics, automotive electronics and AI hardware.
Solar manufacturing: Moving upstream
India has rapidly established itself as a major solar manufacturing base, but the next stage is about going deeper into the value chain.
Jefferies identifies India as the world’s second largest solar PV manufacturer, with around 35GW of solar cell capacity already operational and another approximately 100GW under construction.
The policy push is increasingly aimed at backward integration across cells, wafers and ingots. Measures including the Approved List of Models and Manufacturers, domestic content requirements and production linked incentives are encouraging manufacturers to localise more of the solar supply chain.
Jefferies expects around 90% of the solar manufacturing value chain to be localised by 2030. The strategic importance is clear. India is trying to reduce dependence on imported solar equipment at a time when renewable energy capacity is expanding rapidly. The opportunity is therefore shifting from simply producing modules to building an integrated manufacturing ecosystem stretching from upstream materials to cells and modules.
Aerospace: Made in India, flying global
Aerospace could be another major beneficiary of India’s engineering and precision manufacturing capabilities.
Jefferies describes India as an emerging beneficiary of a global aerospace “demand-supply imbalance”, with the country positioned to leverage its engineering talent, manufacturing capabilities and cost competitiveness. Global demand provides a powerful backdrop.
Airbus estimates that the world’s passenger aircraft fleet could nearly double from around 23,000 aircraft in 2025 to 46,000 by 2045, requiring around 42,000 new aircraft over the period. Meanwhile, the global aerospace industry has a backlog of more than 17,000 aircraft, equivalent to around 12 years of current production capacity. India is already part of this supply chain.
Exports under HS Code 88, covering aircraft, spacecraft and parts, increased nearly five fold from $1.4 billion in FY20 to $7 billion in FY25. Boeing sources more than $1.4 billion annually from over 375 Indian suppliers, while Airbus sources more than $1.6 billion of components and services from India and is targeting $2 billion before 2030. Safran has also announced plans to increase component sourcing from India to $580 million by 2030.
The supplier base is expanding across aerostructures, engine components, aircraft systems, electrical interconnects and precision tooling.
India could also capture a larger share of the aircraft maintenance market as its domestic fleet expands. Jefferies points to policy measures including 100% FDI and changes in taxation of aircraft and engine parts, alongside investments by companies such as Airbus, HAL, Safran and IndiGo in the MRO ecosystem.
The common thread: Moving up the value chain
The six industries may appear unrelated, but Jefferies’ report reveals a common theme. The country is trying to move from being a large market and manufacturing destination to becoming a deeper part of the global technology value chain.
In space, that means private companies moving from experimentation to commercial operations. In semiconductors, it means moving from design services and imported chips towards fabs, packaging, materials and indigenous chip design. In data centres, it means building the physical infrastructure required for cloud computing and AI. In electronics, it means moving from assembly towards components. In solar, it means moving upstream from modules towards cells, wafers and ingots. And in aerospace, it means moving deeper into global OEM and Tier 1 supply chains.