
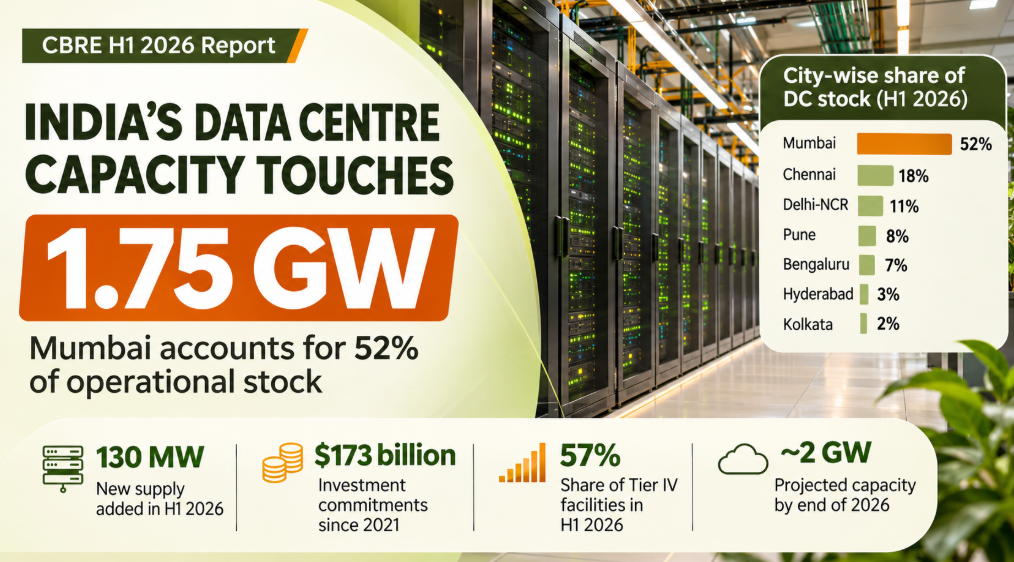
The country’s data centre industry reached an operational capacity of nearly 1,750 MW by the end of the first half of 2026, with around 130 MW of fresh supply added during the January-June period, as demand for cloud computing, artificial intelligence (AI) and digital services continues to drive infrastructure investments.
According to CBRE Research’s September 2026 report, Beyond Growth: India’s Rise Among APAC’s Leading Data Centre Markets, Mumbai accounted for 52% of India’s total operational data centre stock, equivalent to around 0.9 GW, followed by Chennai with an 18% share. Delhi-NCR contributed 11%, Pune 8%, Bengaluru 7%, Hyderabad 3% and Kolkata 2%.
The report noted that India’s data centre market has advanced from the ‘High Growth Market’ category to APAC’s ‘Leading Data Centre Markets’ category in 2026, joining Japan, Australia and Mainland China. The transition reflects the increasing scale and maturity of India’s digital infrastructure ecosystem.
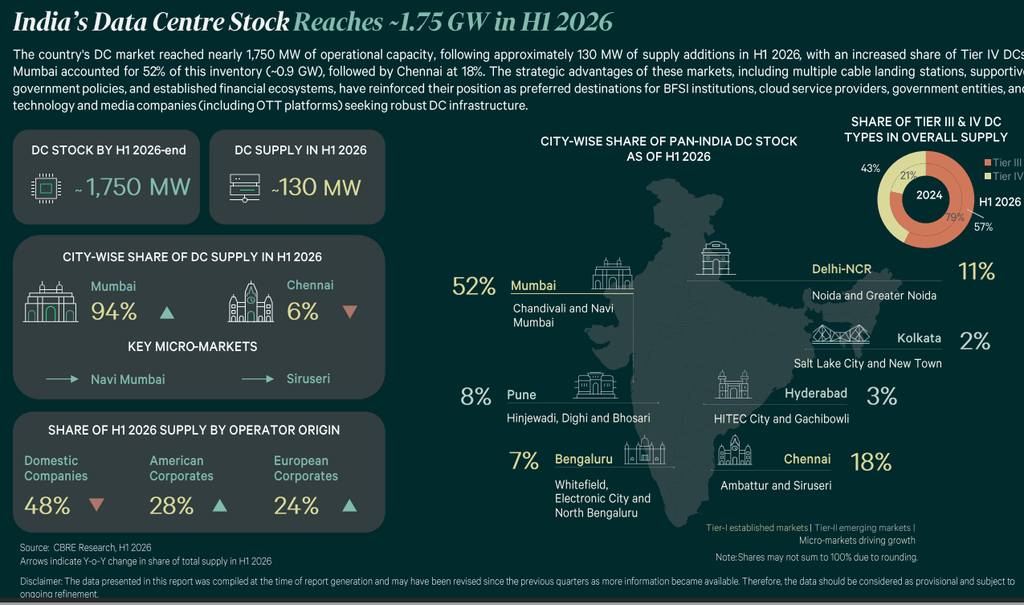
Mumbai and Chennai continue to attract operators because of their connectivity infrastructure, multiple cable landing stations, supportive government policies and established financial ecosystems. These markets remain preferred destinations for banking and financial services institutions, cloud service providers, government entities and technology companies.
The concentration of supply in established markets, however, is gradually giving way to opportunities in emerging locations. CBRE’s analysis identifies Noida and Greater Noida, Navi Mumbai, Siruseri, Hinjewadi, Whitefield and Gachibowli among the key micro-markets supporting expansion.
The composition of India’s data centre infrastructure is also changing. Tier IV facilities accounted for 57% of overall supply in H1 2026, compared with 21% in 2024, while Tier III facilities’ share declined from 79% to 43%, indicating a growing preference for higher-reliability infrastructure.
Domestic companies accounted for 48% of the supply added during H1 2026, while American and European corporates contributed 28% and 24%, respectively.
The investment pipeline remains substantial. CBRE estimates that India attracted around $38 billion in data centre investment commitments during H1 2026, taking cumulative commitments since 2021 to approximately $173 billion.
The report also highlights the scale of planned expansion. As many as 92% of surveyed data centre operators plan to add more than 100 MW of capacity over the next 24 months. Of these, 75% are considering additions exceeding 250 MW.
Power availability, network connectivity and sustainability are emerging as important considerations. Renewable sources currently meet 30-40% of operational energy requirements for most surveyed operators. Meanwhile, AI workloads are expected to increase rack power density requirements to around 30-50 kW, against 8-10 kW in traditional facilities.
CBRE expects more than 200 MW of additional capacity in the second half of 2026, potentially taking India’s operational data centre capacity close to 2 GW by the year-end.


