
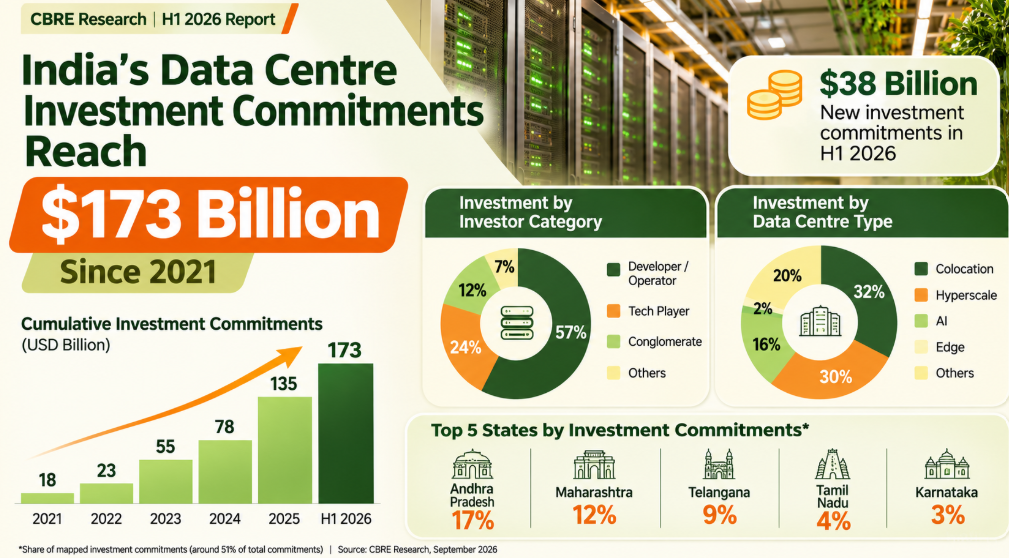
Data centre, which is considered as another sunrise sector in India, attracted investment commitments of around $38 billion during the first half of 2026, taking cumulative commitments since 2021 to $173 billion, as rising demand for cloud computing, artificial intelligence (AI) and digital infrastructure drives investor interest in the country.
According to CBRE Research’s September 2026 report, Beyond Growth: India’s Rise Among APAC’s Leading Data Centre Markets, cumulative investment commitments in the sector have increased from $18 billion in 2021 to $23 billion in 2022, $55 billion in 2023, $78 billion in 2024 and $135 billion in 2025, before reaching $173 billion by H1 2026.
The report attributes the sustained investment momentum to increasing cloud adoption, AI-related demand and ongoing digitalisation initiatives. Data centres have also emerged as an attractive asset class for investors across Asia Pacific, ranking as the fourth most preferred asset class in CBRE’s 2026 Asia Pacific Investor Intentions Survey.
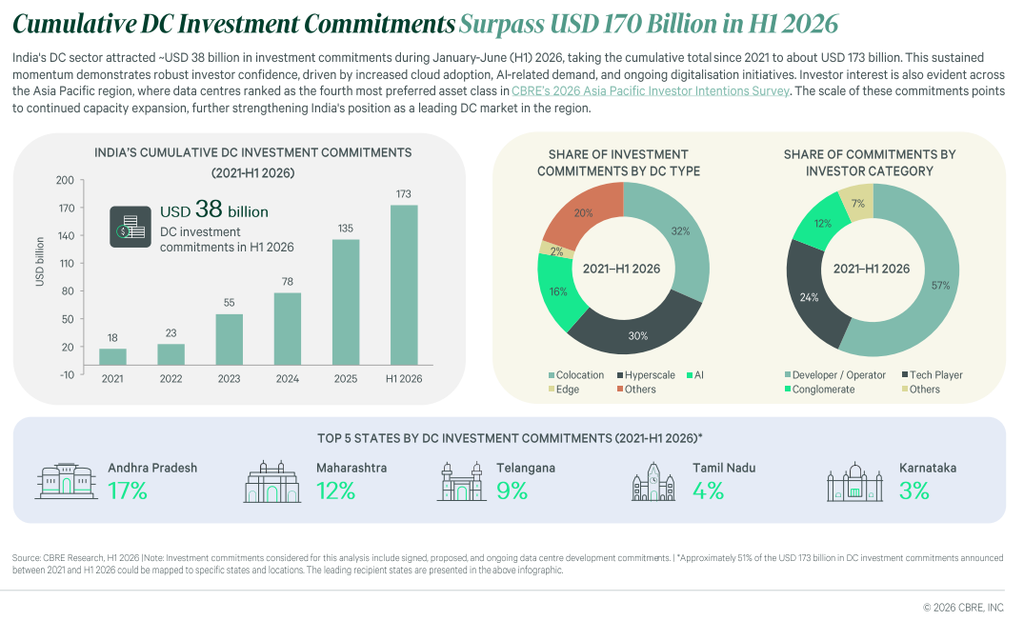
A breakdown of cumulative commitments shows that developers and operators accounted for 57% of the total investment, while technology players contributed 24% and conglomerates 12%. Other investor categories accounted for the remaining 7%, highlighting the growing participation of both infrastructure specialists and technology companies in the sector.
By data centre category, colocation facilities attracted the largest share of commitments at 32%, closely followed by hyperscale projects at 30%. AI-focused data centres accounted for 16%, while edge facilities represented 2%. Other categories made up the remaining 20%.
The geographical distribution of investments also points to a broader expansion beyond traditional data centre hubs. Andhra Pradesh emerged as the largest recipient state, accounting for 17% of mapped investment commitments between 2021 and H1 2026. Maharashtra followed with 12%, Telangana with 9%, Tamil Nadu with 4% and Karnataka with 3%.
However, the report noted that only around 51% of the total $173 billion in announced commitments could be mapped to specific states and locations. The investment figures include signed, proposed and ongoing data centre development commitments and should not be interpreted as capital already deployed.
CBRE also highlighted a shift in investment strategies. While multi-city portfolios dominated commitments between 2021 and 2023, accounting for more than 60% in most years, Hyderabad gained traction in 2024 and 2025, attracting 23% and 15% of commitments, respectively. Tier II cities also secured 16% and 27% of capital deployment in these two years.
In H1 2026, multi-city investment strategies regained prominence, accounting for more than 85% of total commitments.
The expanding investment pipeline underscores India’s growing importance in the Asia Pacific data centre market, with investors increasingly looking beyond established hubs to build capacity for the next phase of digital and AI-led growth.


