
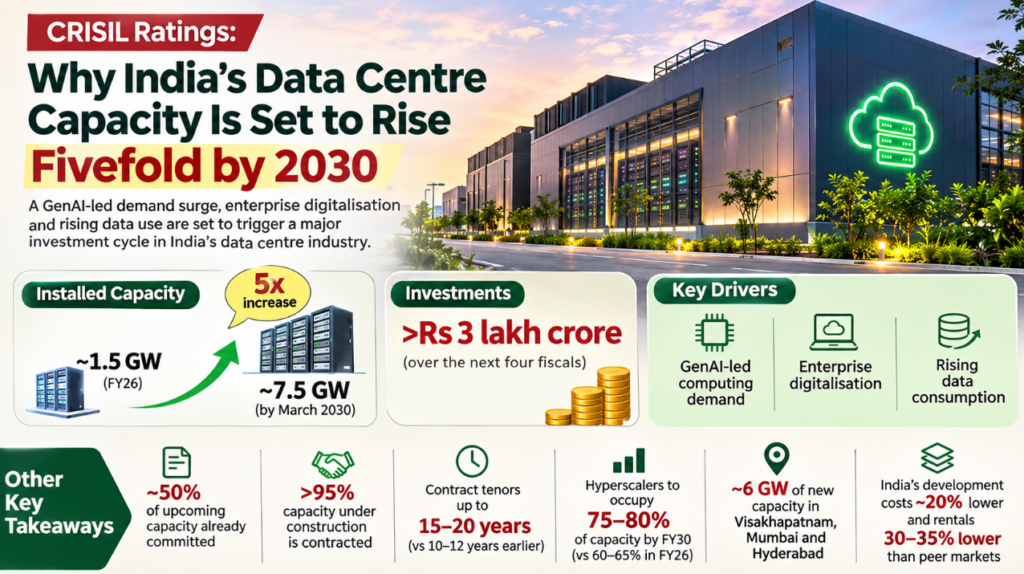
The country’s data centre industry is entering an investment supercycle. Installed capacity is expected to increase five-fold to about 7.5 gigawatts (GW) by March 2030, attracting investments of more than Rs 3 lakh crore over the four fiscals. The surge is being driven by generative artificial intelligence (GenAI) led computing demand, enterprise digitalisation and rising data consumption. While long-tenor contracts with hyperscalers provide strong cash flow visibility, the pace of this expansion and credit quality of the data centre developers will hinge on timely power connectivity, regulatory approvals and disciplined project execution.
Demand visibility is strong for an industry undertaking such a capital-intensive expansion. Nearly half of the upcoming capacity is already committed under long-term contracts, limiting speculative development and reducing offtake risk. Upfront tie-ups with hyperscalers, driven by cloud adoption and compute-intensive GenAI workloads, provide revenue certainty from the outset. This helps de-risk projects, even as the scale and speed of the planned build-out intensify execution requirements.
Says Anand Kulkarni, Director, Crisil Ratings, “India’s structural cost advantages further strengthen its attractiveness as a data centre destination. Development costs are around one-fifth lower than in several competing Asia-Pacific markets owing to more competitive land, construction and labour costs. Combined with lower power tariffs, this translates into rentals that are 30-35% lower than in peer markets. The ability to develop large, renewable-powered campuses also aligns well with the sustainability goals of hyperscalers, reinforcing India’s competitive positioning.”
However, this unprecedented growth in development is also creating power infrastructure bottleneck. About three-fourths of upcoming capacity of around 6 GW is expected to be built in Visakhapatnam, Mumbai and Hyderabad. By fiscal 2030, data centre capacity in these cities could rise sharply and equate to around 80%, 60% and 20%, respectively, of their current peak power demand. This underscores the criticality of timely grid connectivity and transmission augmentation.
Against this backdrop, disciplined growth backed by firm contracts provides an important safeguard for the developers. Existing facilities in India are operating at about 90% utilisation, and more than 95% of capacity currently under construction is already contracted. This should support faster ramp-up in cash flows once projects are commissioned.
Nitin Bansal, Associate Director, Crisil Ratings said, “The quality of contracted revenues has also strengthened. Contract tenors have lengthened to 15-20 years from 10-12 years earlier, enhancing cash flow visibility. Furthermore, high migration costs and rising replacement capex should support customer retention, although a meaningful contract renewal track record is yet to be established. At the same time, developers will need to ensure that existing facilities remain relevant for next-generation GenAI workloads through timely investments in upgrades to support higher power density and advanced cooling infrastructure.”
Even so, the hyperscaler dominance that underpins demand visibility also creates customer concentration and pricing risk for the developers. The capacities leased by hyperscalers are expected to account for 75-80% of industry capacity by fiscal 2030, up from 60-65% in fiscal 2026. While pricing has remained broadly stable so far, as capacity additions accelerate and hyperscalers gain greater bargaining power, any pressure on rentals may weaken project returns.
From a credit perspective, the sector’s profile will be shaped by the interplay between strong contracted cash flows and front-loaded leverage arising from large upfront capital expenditure. Debt levels are expected to remain elevated over the medium term because investments typically precede cash generation by 24-36 months. Nevertheless, as projects are commissioned and utilisation ramps up, strong cash flows should support a gradual improvement in leverage.
Overall, contracted revenues provide a strong anchor for credit stability, but the unprecedented scale of capacity addition brings execution into sharper focus. Timely commissioning, cost control, adequate power availability and the sustainability of GenAI-led demand growth will remain the key factors determining how successfully the industry navigates this investment cycle.
Frequently asked questions (FAQs)
Q1. How much will India’s data centre capacity increase by 2030?
India’s installed data centre capacity is expected to increase fivefold to approximately 7.5 GW by March 2030, according to CRISIL Ratings.
Q2. How much investment is expected in India’s data centre industry by 2030?
The industry is expected to attract investments exceeding Rs 3 lakh crore over the four fiscals leading up to March 2030.
Q3. What are the key factors driving India’s data centre growth?
The major growth drivers include generative AI workloads, cloud computing, enterprise digitalisation, rising data consumption and increasing demand from global hyperscalers.
Q4. Which Indian cities will drive data centre capacity expansion?
Visakhapatnam, Mumbai and Hyderabad are expected to account for around three-fourths of the upcoming data centre capacity of approximately 6 GW.
Q5. Why are hyperscalers important for India’s data centre industry?
Hyperscalers provide long-term demand visibility through capacity leasing agreements. Their contracts help developers secure revenue visibility, reduce offtake risks and support financing for capital-intensive projects.
Q6. What are the biggest challenges facing India’s data centre industry?
Key challenges include timely power connectivity, transmission infrastructure, regulatory approvals, high capital expenditure, project execution and customer concentration risks.
Q7. How long are data centre contracts in India?
According to CRISIL Ratings, contract tenures have increased to 15-20 years from 10-12 years earlier, improving revenue visibility for developers.
Q8. What role will generative AI play in India’s data centre expansion?
Generative AI requires significant computing power, advanced servers, high-density infrastructure and sophisticated cooling systems. This is expected to increase demand for data centre capacity in India.


