
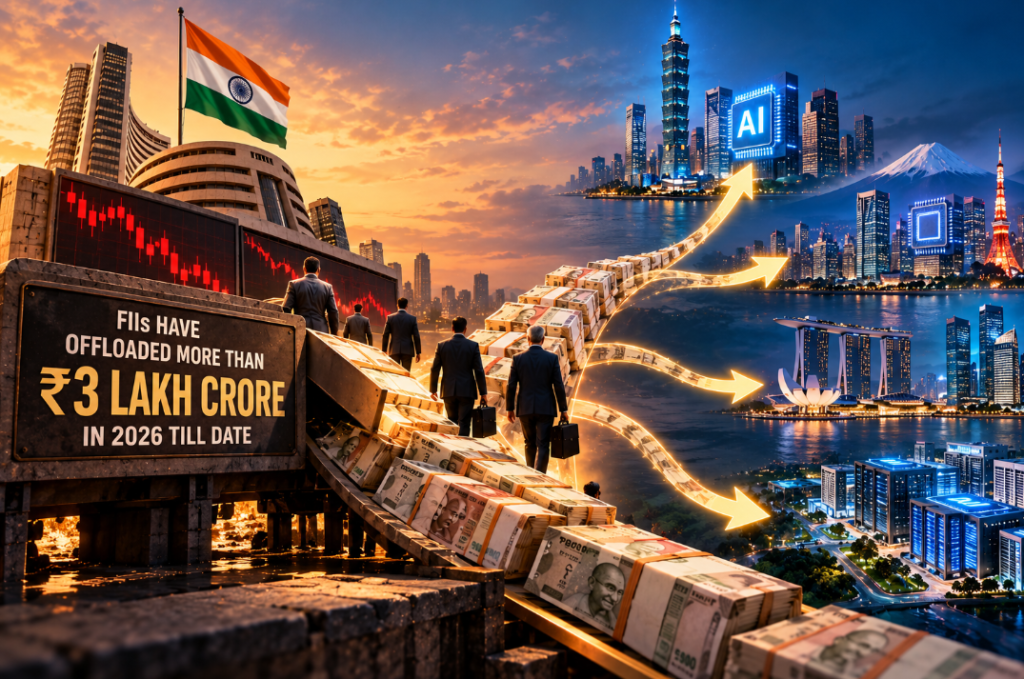
The domestic stock market is facing a problem that goes beyond valuations, crude oil prices or geopolitical uncertainty. As global investors reposition portfolios around artificial intelligence, semiconductors and advanced technology, India risks missing out on a growing pool of international capital because its listed markets offer relatively limited direct exposure to these themes.
A report by PL Capital, titled India Strategy: The Perfect Storm: Rising Macro and Geopolitical Risks, flags this challenge at a time when foreign institutional investors (FIIs) are putting sustained pressure on Indian equities.
“With US treasury rate at 5.3%, India is unlikely to attract big FII money in near term,” the brokerage said in its October 9 report. It identified three key reasons which are limited investment opportunities in emerging technology themes, modest dollar adjusted market returns over the past five years, and the possibility of a slowdown in domestic demand as inflation and interest rates rise.
Foreign institutional investors have offloaded shares worth around Rs 3.08 lakh crore in the ongoing calendar year till October 11, 2026.
The report’s warning highlights a structural challenge for India. The country may be building its technology capabilities, but global investors are looking for businesses that can capture a meaningful share of the AI and semiconductor value chain today.
The AI investment gap
PL Capital said global capital flows are being attracted to emerging technology themes such as semiconductors, AI and technology, where the country does not yet have enough direct investment opportunities in listed companies.
“Indian companies are catching up in these segments but they are at a nascent stage in Semiconductors and AI and Data centres, we are more at the commodity end of the market,” the report said.
That distinction matters. Building data centres, assembling electronic products or supplying equipment can create substantial business opportunities. However, investors seeking exposure to the highest growth and profit pools of the AI economy may prefer companies that design advanced chips, develop critical computing technologies or own differentiated platforms.
India’s opportunity is not absent. Its semiconductor manufacturing ambitions, expanding data centre capacity and technology services industry could create new investment avenues. The challenge is whether these businesses can scale quickly enough, build competitive advantages and become sufficiently large and liquid to attract global institutional investors.
For now, the gap between India’s technology ambitions and the investment opportunities available in its listed market could be weighing on its appeal.
Returns are competing with US bonds
Technology exposure is only part of the problem. Global investors also compare the potential returns from equities with those available from safer assets.
With US Treasury yields at 5.3%, domestic equities must offer a compelling risk adjusted return to attract fresh foreign money. PL Capital noted that the Nifty 100 delivered a compound annual growth rate of just 1.2% in dollar adjusted returns over the preceding five years.
For overseas investors, rupee returns are not the whole story. Currency movements can erode gains, while higher US bond yields increase the opportunity cost of investing in riskier emerging markets.
The brokerage also noted that foreign flows into Indian equities have been “very patchy since 2021”. A strong domestic growth story, therefore, does not automatically translate into sustained foreign buying. Prabhudas Lilladher in its report added that as India does not have direct plays in emerging technology themes which are attracting big global flows (semicon, AI and technology), Indian markets might continue to see volatile capital flows, more so in an environment of rising crude, interest rates, deficient monsoon and super El Nino impact on global Agri commodities.
A difficult macro backdrop
The technology gap is colliding with near term economic risks. PL Capital highlighted a 13% monsoon deficit, rising inflation linked to crude oil and agricultural commodities, and a shift towards tighter monetary policy.
The report warned that inflationary pressures could eventually weaken domestic demand, even though demand conditions had remained resilient at the time of its assessment.
These risks make the investment case more complicated: global investors are weighing both the opportunity cost of high US yields and uncertainty around India’s earnings outlook.
Can India turn the tide?
The report does not suggest that India has lost its long-term appeal. It noted that the Nifty 50’s one year forward price to earnings multiple was at a 19% discount to its 15 year average, which could help limit further downside.
But cheaper valuations alone may not be enough to trigger a durable return of foreign capital. Investors will also look for earnings growth, currency stability and stronger exposure to the industries shaping the next phase of global growth.
For India, the next leg of market leadership may depend partly on how quickly its semiconductor, AI and data centre businesses move from early-stage capacity building to scaled, differentiated and investable companies.
The larger question is whether India can convert its technology ambitions into listed investment opportunities that global funds cannot afford to ignore. Until then, the country’s growth story may remain compelling, while international capital looks elsewhere for a more direct route into the AI boom.


