
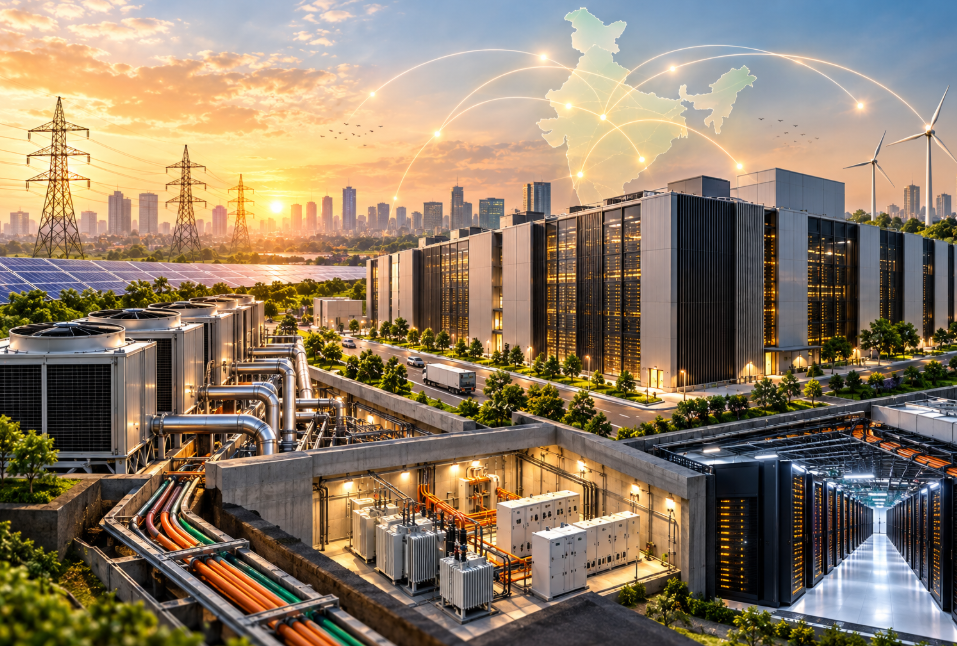
India’s data centre expansion is rapidly turning into a much bigger infrastructure story than the growth of cloud computing alone. As artificial intelligence, cloud adoption, enterprise digitisation and data-localisation requirements push demand for computing capacity higher, the country is entering a new phase of investment that could create opportunities across power equipment, cooling systems, construction, real estate and network infrastructure.
A recent report by Jefferies estimates that the country’s colocation data-centre capacity, which has expanded five-fold over the past five years to around 2GW, could grow another five-fold to roughly 10GW over the next five years. The expansion represents a $9 billion revenue opportunity for data-centre operators and a $45 billion facility investment opportunity across power, cooling, construction and network infrastructure.
For investors looking beyond the data-centre operators themselves, the bigger question is: who supplies the infrastructure needed to build and power these facilities?
From 2GW to nearly 10GW
India’s data-centre market is still at an early stage. Jefferies estimates that colocation capacity stood at around 2,076MW in 2026 and could reach around 9,576MW by 2031. The demand is being driven by several structural factors. Hyperscalers account for around 60% of current demand, while BFSI contributes roughly 15%. At the same time, utilisation levels of existing facilities are estimated at 95-97%, creating the need for significant new capacity.
Mumbai and Chennai have emerged as key data-centre hubs because of their connectivity and access to submarine cable landing stations. The next phase of growth is also expected to involve new investments from players including AdaniConneX, Bharti Airtel and TCS.
India’s relatively attractive economics are another factor. Jefferies notes that power costs and capital expenditure requirements for data centres are, on average, 25-40% lower in India. Government policy, including a 20-year tax holiday for cloud providers, along with data-localisation requirements, is also supporting the country’s ambition to become a regional data-centre hub.
The real opportunity
The headline $45 billion opportunity is spread across the physical infrastructure required to make a data centre operational. Jefferies breaks the estimated cumulative CY27-31 facility capex into roughly $11 billion for electrical/power infrastructure, $9 billion for mechanical/racks and fit-outs, $16 billion for cooling and $7 billion for network infrastructure.
That means the data-centre buildout creates a large addressable market for companies supplying equipment and services even if they do not own or operate a data centre themselves. The distinction is important. A data centre may be operated by a company such as Airtel, AdaniConneX or another specialist operator, but its construction requires transformers, switchgear, transmission and distribution equipment, backup generators, cables, cooling systems, HVAC equipment, network infrastructure and construction services.
In other words, every additional megawatt of data-centre capacity creates a chain of equipment and infrastructure demand around it.
Power is at the centre of the opportunity
Among all these segments, power infrastructure stands out because data centres cannot function without reliable and uninterrupted electricity. Jefferies estimates that power-related costs account for around 30% of data-centre costs, making electricity supply and backup power a critical part of the investment cycle.
Automation, HVAC/cooling and EPC each account for around 15%, while backup gensets account for approximately 5-10% of costs.
This makes companies supplying transmission and distribution equipment, electrical systems and backup generation particularly relevant to the data-centre buildout.
Jefferies identifies Hitachi Energy, Siemens Energy and GE Vernova T&D as having the highest exposure to data-centre capex among the power and T&D companies covered by the brokerage.
It then identifies ABB India and Siemens India as other companies with exposure, although Jefferies notes that their products face comparatively higher competitive pressure than those of the T&D players.
Hitachi Energy
Hitachi Energy is one of the clearest beneficiaries of the power infrastructure buildout identified by Jefferies. As data centres become larger and more power-intensive, their requirements extend beyond simply securing electricity. They require reliable transmission, distribution, transformers, switchgear and electrical systems capable of supporting high-density loads.
The scale of India’s expected capacity addition therefore creates a broader opportunity for power-equipment suppliers as utilities, developers and data-centre operators invest in electrical infrastructure.
Siemens Energy and GE Vernova T&D
The same trend extends to Siemens Energy and GE Vernova T&D. India’s data-centre expansion requires not only electricity generation but also the infrastructure to transmit and distribute that electricity reliably to increasingly concentrated loads.
This places T&D equipment suppliers directly within the investment chain created by the data-centre boom.
Backup power creates another pool of demand
A data centre cannot afford prolonged power interruptions. As a result, backup generation becomes an important component of the infrastructure.
Jefferies identifies Cummins India as particularly relevant, noting that the company has the highest market share in genset supplies in India, supported by its multinational parentage.
Kirloskar Oil Engines is another company to watch within this segment. Jefferies says the company has recently won an order from an Indian company setting up a data centre and that successful execution could make it a relevant player in the segment.
This creates a second layer of the data-centre power opportunity: companies do not only need grid connectivity; they also need reliable backup generation to ensure uninterrupted operations.
Cables and electrical equipment join the chain
The investment opportunity also extends to companies supplying cables and electrical infrastructure. Jefferies’ data-centre beneficiary list includes Polycab India, KEI Industries and Finolex Cables, which can participate in the broader electrical infrastructure buildout.
The opportunity is not limited to high-voltage equipment. Data centres require extensive electrical distribution systems within facilities, creating demand across multiple layers of the electrical supply chain.
Other companies listed by Jefferies under its data-centre theme include Havells and TARIL.
Cooling becomes increasingly important
Electricity is only one part of the data-centre equation. High-density computing generates enormous amounts of heat, making cooling systems an essential component of modern facilities.
Jefferies estimates cooling to represent around $16 billion of the cumulative $45 billion facility-capex opportunity over CY27-31, making it the largest individual category in its value-chain breakdown.
This brings companies such as Voltas and Blue Star into the broader data-centre infrastructure opportunity.
The importance of cooling is expected to increase as data centres become larger and more power intensive. Jefferies specifically highlights energy-efficient cooling technologies as an increasingly important requirement for future facilities.
Construction and real estate
The data-centre boom also requires land, buildings and physical infrastructure. Jefferies estimates approximately $9 billion of the cumulative facility-capex opportunity in the mechanical/racks and fit-out category, while the broader ecosystem also creates opportunities for construction companies and real-estate developers.
Lodha Developers and Anant Raj appear in Jefferies’ list of companies associated with the data-centre theme.
The underlying opportunity is straightforward: as capacity expands from roughly 2GW to nearly 10GW, developers need to build new facilities and associated infrastructure.
Network infrastructure
Data centres also depend on high-speed connectivity. Their customers need reliable connections between facilities, cloud platforms, enterprises and users.
Jefferies estimates around $7 billion of cumulative CY27-31 capex for network infrastructure.
Companies such as HFCL and Sterlite Technologies are therefore part of the wider data-centre infrastructure opportunity identified by the report, alongside cable companies that can participate in the physical connectivity buildout.
Who operates the data centres?
While infrastructure suppliers may capture a significant portion of the physical investment, the operators themselves are also positioned to benefit from the expansion.
Jefferies estimates that the growth in colocation capacity could create around $9 billion of revenue opportunity for data-centre operators, with annual data-centre rental revenue rising from about $2 billion in 2026 to roughly $9.3 billion by 2031.
The report’s player-wise capacity analysis includes AdaniConneX, NTT GDC, TCS, Princeton Digital, Airtel Nxtra, Sify, CtrlS, Yotta, STT GDC, Iron Mountain, Anant Raj and Lodha, among others.
The market is also changing structurally. While telecom companies have historically dominated India’s data-centre landscape, Jefferies notes that conglomerates, IT companies and real-estate players are increasingly entering the segment.
The $45 billion opportunity in one view
Where the $45 Billion Data-Centre Capex Could Go
Jefferies estimated facility capex across key data-centre infrastructure segments for CY27–31.


